Published · By Jeff Brick, 2026 SDMLS President
Quick answer: Wildfire zones matter for San Diego County home insurance, but not in the way most people think. CAL FIRE’s Fire Hazard Severity Zone maps measure hazard, and California’s Department of Insurance says those maps do not set your premium. What insurers actually price is your home’s risk, which you can lower with a Class A roof, ember-resistant vents and a clear five-foot zone around the house. If private carriers say no, the California FAIR Plan is the backstop, and its rates rose an average of 29.1% starting Oct. 15, 2026. Get quotes early, before you write an offer.
This week in San Diego real estate
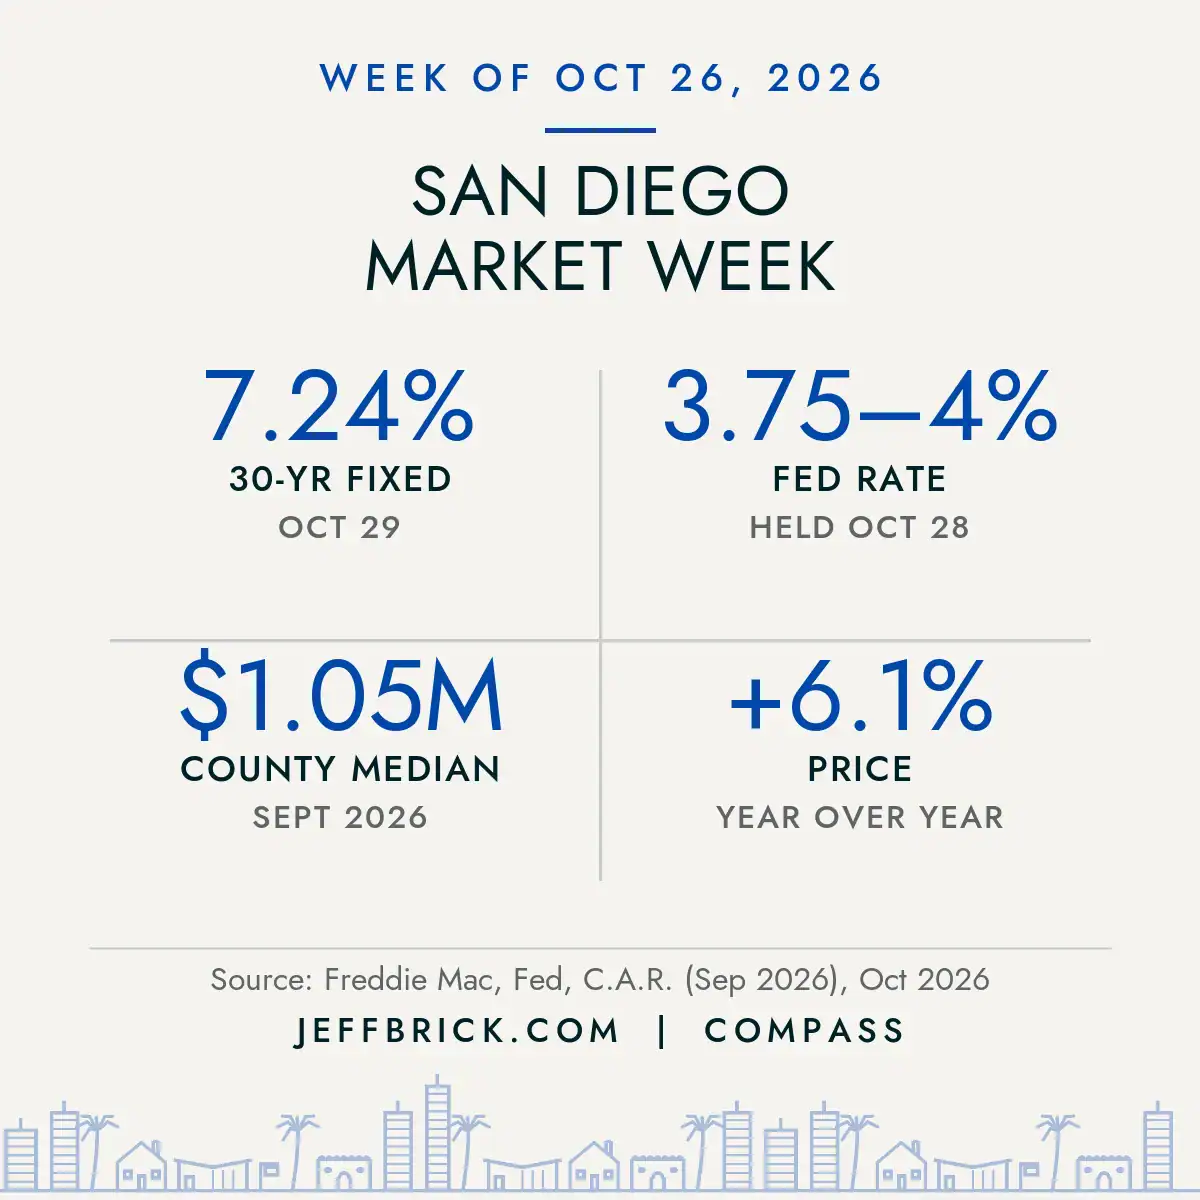
Rates eased a little and the Fed sat tight. Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed at 7.24% on Oct. 29, 2026, down from 7.32% the week before but still well above the 6.17% of a year ago (WRE News reported the same figures). The 15-year fixed averaged 6.60%.
On Oct. 28, the Federal Reserve held its target range at 3.75% to 4% on a 10–2 vote, with two members preferring a hike, as Fox Business also reported. For buyers, that means no quick relief on rates is promised.
Prices are holding up even as sales slow. The San Diego County median for an existing single-family home was $1,050,000 in September, up 6.1% from a year earlier, while sales fell 12.2%, per the California Association of REALTORS® (Oct. 19, 2026) and 10News. San Diego MLS data compiled by SDAR shows a September detached median of $1,079,000 (up 5.8%) and an attached median of $670,000 (down 0.2%). In the city of San Diego, Redfin reports homes selling in a median 28 days.
Want the full rate picture? See my breakdown of what higher San Diego mortgage rates cost you.
Q&A: How do wildfire zones affect home insurance in San Diego County?
What the fire hazard maps are, and what they are not
California’s Office of the State Fire Marshal maps land as Moderate, High or Very High Fire Hazard Severity Zones. The key line on the State Fire Marshal’s page: the maps “evaluate ‘hazard,’ not ‘risk.'” Hazard looks at the land, weather and fuel without counting home hardening or brush clearing. Risk is the damage a fire could actually do once those improvements are counted.
The 2025 update was the first in well over a decade, and San Diego County saw a 26% increase in acreage rated “very high,” as reported by KPBS and 10News. The State Fire Marshal links to a Department of Insurance consumer alert titled “CAL FIRE Hazard Maps Do Not Affect Insurance Rates or Availability.” In other words, a new zone line on a map is not, by itself, why your premium changes.
Where the zone does matter: disclosures and defensible space
When you buy, California’s Natural Hazard Disclosure statement (Civil Code 1103.2) tells you whether the home sits in a Very High Fire Hazard Severity Zone. Read it the day you get it. You can also look up any address on the State Fire Marshal’s map viewer, linked from the page above, before you even tour a home.
What insurers reward: the “Safer from Wildfires” steps
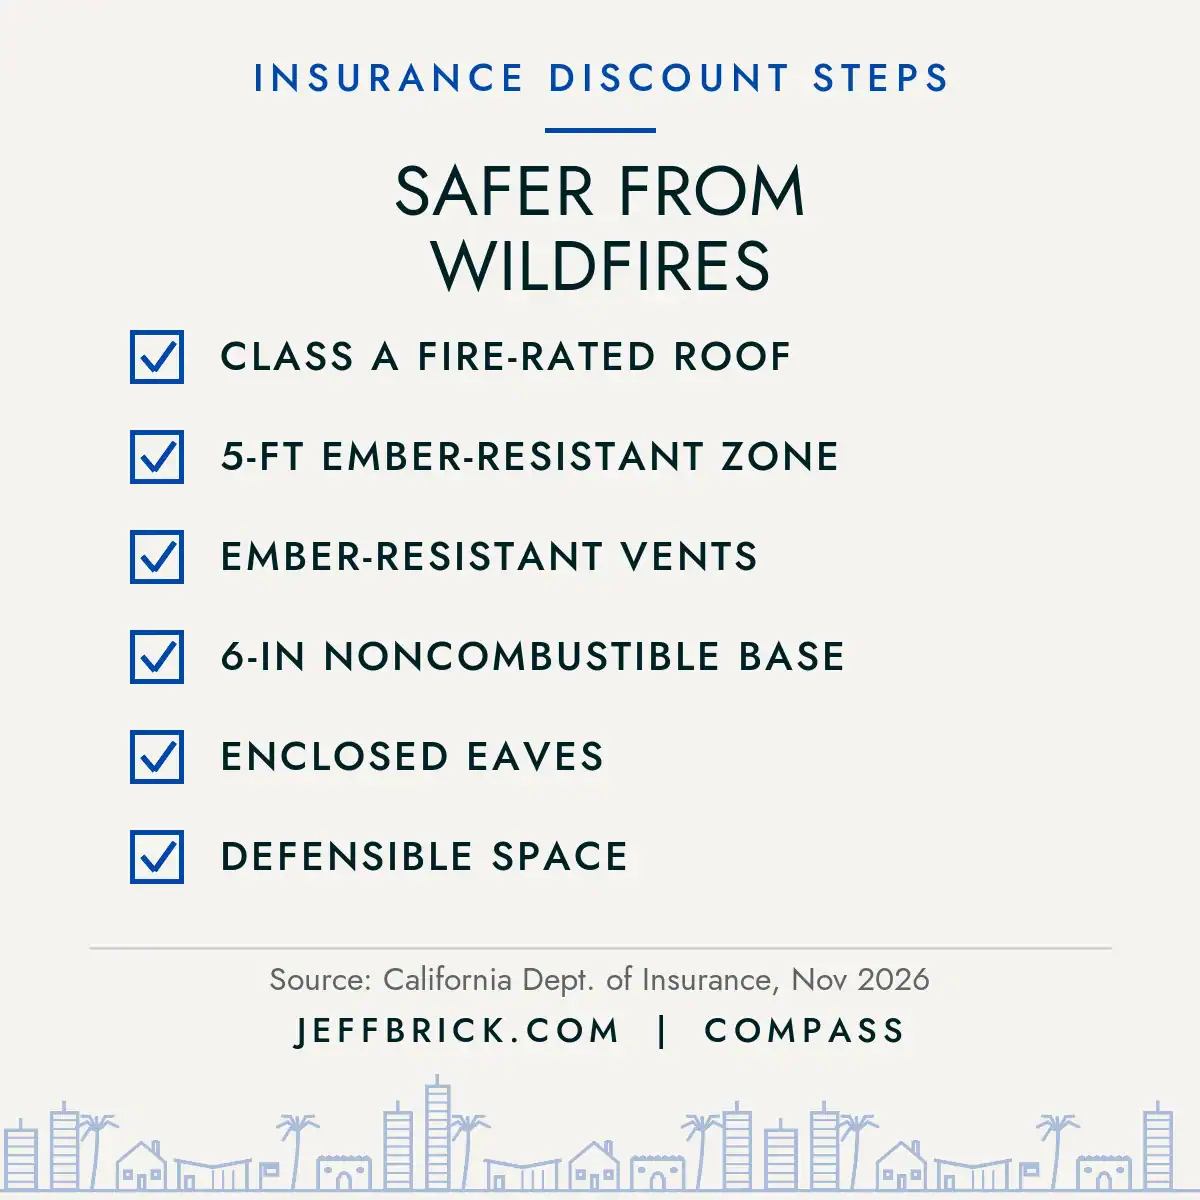
The California Department of Insurance’s Safer from Wildfires framework lists the mitigation that counts toward discounts, and states that “every action under Safer from Wildfires will qualify you for an insurance discount.” The list includes a Class A fire-rated roof, a five-foot ember-resistant zone (fencing included), ember- and fire-resistant vents, six inches of noncombustible material at the base of exterior walls, enclosed eaves, upgraded windows, clearing under decks, moving combustible sheds at least 30 feet away and meeting defensible space rules. CAL FIRE calls the first five feet around a home “the most important” zone.
When private carriers say no: the FAIR Plan
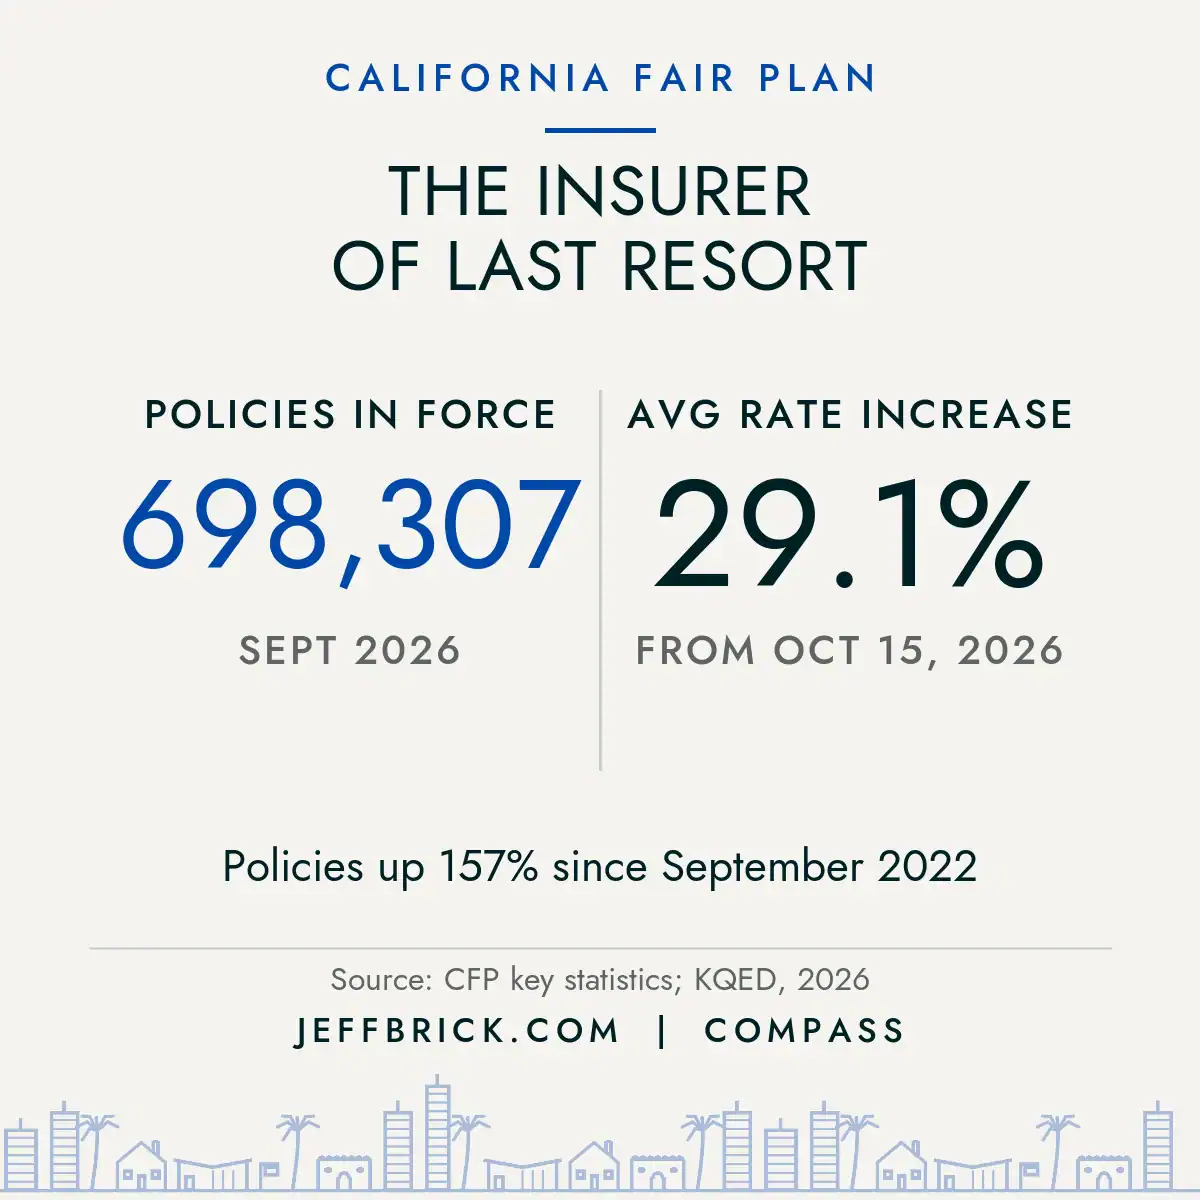
The California FAIR Plan is the insurer of last resort. As of September 2026 it had 698,307 policies in force, up 8% in a year and 157% since September 2022, according to its own key statistics. Its average rates rose 29.1% starting Oct. 15, 2026, reported by KQED and InsuranceNewsNet; not every policyholder sees that exact change. The FAIR Plan dwelling policy is a named-peril policy (fire, lightning, internal explosion, smoke), so most owners pair it with a Difference in Conditions policy for broader coverage. Growth isn’t only in the backcountry: Stanford researchers at CEPP found that by June 2026, 55% of FAIR Plan policies were outside wildfire-distressed areas.
What this means for buyers
- Quote insurance before you offer. In East County, North County inland and canyon-edge neighborhoods, call an independent broker as soon as you’re serious about a home.
- Budget for the full premium. A FAIR Plan policy plus a Difference in Conditions policy is two bills. Build both into your monthly payment, along with the numbers in my guide to how much you need to buy a home in San Diego.
- Ask for the mitigation file. Roof age and class, vent type and defensible space work can all affect your quote.
- Use your inspection period. If insurance comes back far higher than expected, that’s information you can negotiate with.
What this means for sellers
If your home is in a higher-hazard area, insurability is now part of your marketing. Gather proof of your roof’s class, vent upgrades and brush clearing, and share your current carrier with buyers’ agents early. Some of the smart, low-cost items in my what to fix before selling guide overlap with the Safer from Wildfires list, such as clearing debris and cleaning up the first five feet around the house.
A quick note for renters and investors
Renters: your landlord’s policy covers the building, not your belongings, so a renters policy is worth pricing. Investors: higher premiums go straight to your cash flow, so get a real quote before you run the numbers on any rental.
Jeff’s take
As 2026 President of the San Diego Multiple Listing Service, a 2024–2026 Director of the San Diego Association of REALTORS®, and the largest luxury apartment home leasing broker in Southern California, I’ve seen more deals wobble over insurance this year than over inspection items. The fix isn’t panic, it’s sequence: check the hazard map, get a quote, then write the offer. Homes with a Class A roof, ember-resistant vents and a clean five-foot zone are easier to insure and easier to sell. Know the numbers early and you can still buy with confidence, even in a wildfire zone. That’s “Million Dollar Service at All Price Points.”
Buying or selling in a fire zone? Let’s plan it
Call or text me at 858-324-4448 and I’ll help you check a home’s hazard zone, connect you with independent insurance brokers and build insurance into your offer or listing strategy. Jeff Brick, REALTOR®, Compass, DRE# 02156850.
FAQ: Home insurance and wildfire zones in San Diego
Does being in a Very High Fire Hazard Severity Zone raise my insurance rate?
Not directly. The State Fire Marshal’s maps measure hazard, and the Department of Insurance says the maps do not affect insurance rates or availability. Insurers use their own risk models, which can still lead to higher prices in fire-prone areas.
How do I find out if a San Diego home is in a fire hazard zone?
Enter the address in the State Fire Marshal’s online map viewer, and read the Natural Hazard Disclosure statement you receive when buying.
How much did FAIR Plan rates go up in 2026?
An average of 29.1% starting Oct. 15, 2026. Individual changes vary, and some policyholders see decreases.
What home improvements can lower my wildfire insurance premium?
The Department of Insurance’s Safer from Wildfires list includes a Class A roof, ember-resistant vents, a five-foot ember-resistant zone, enclosed eaves, upgraded windows and defensible space. Each qualifying action earns a discount.
What were San Diego mortgage rates this week?
Freddie Mac’s 30-year fixed average was 7.24% on Oct. 29, 2026, down from 7.32% a week earlier.
This article is general information, not legal, insurance, tax or financial advice. Please confirm your situation with a licensed insurance professional or other appropriate advisor. Market figures are from the sources linked above, as of November 1, 2026.