Published · By Jeff Brick, 2026 SDMLS President
Quick answer: To buy a median-priced San Diego condo or townhome ($670,000 in September 2026), plan on roughly $36,000 to $56,000 in cash with a 3.5% down FHA loan, plus an income around $200,000 to keep the payment comfortable. A median detached house ($1,079,000) takes about $233,000 to $259,000 in cash with 20% down and an income near $290,000. Those figures come from San Diego MLS medians, this week’s 7.32% average 30-year rate and closing costs of 2% to 5% of the loan. Your real number depends on the home, the loan and your debts, so let’s walk through it.
This is general information, not legal, tax or financial advice. Confirm loan terms with a licensed lender and tax questions with your CPA.
What it costs to buy in San Diego right now
Start with price, because everything else is a percentage of it. In September 2026, the median detached home in the San Diego MLS area sold for $1,079,000, up 5.8% from a year earlier, while the median condo or townhome sold for $670,000, essentially flat (down 0.2%). Condo inventory rose 5.8% to 2,734 listings, a 4.0-month supply, versus 2.4 months for houses. For first-time buyers, that gap matters: condos and townhomes are where you have more choices and more room to negotiate.
Rates moved a little in your favor this week. Freddie Mac’s survey put the 30-year fixed at 7.32% on Oct. 22, down from 7.40% the week before, with chief economist Sam Khater calling it “some relief to prospective homebuyers.” The Federal Reserve also meets Oct. 27–28; I covered what to watch in my Fed meeting playbook.
How much income do you need to buy a house in San Diego?
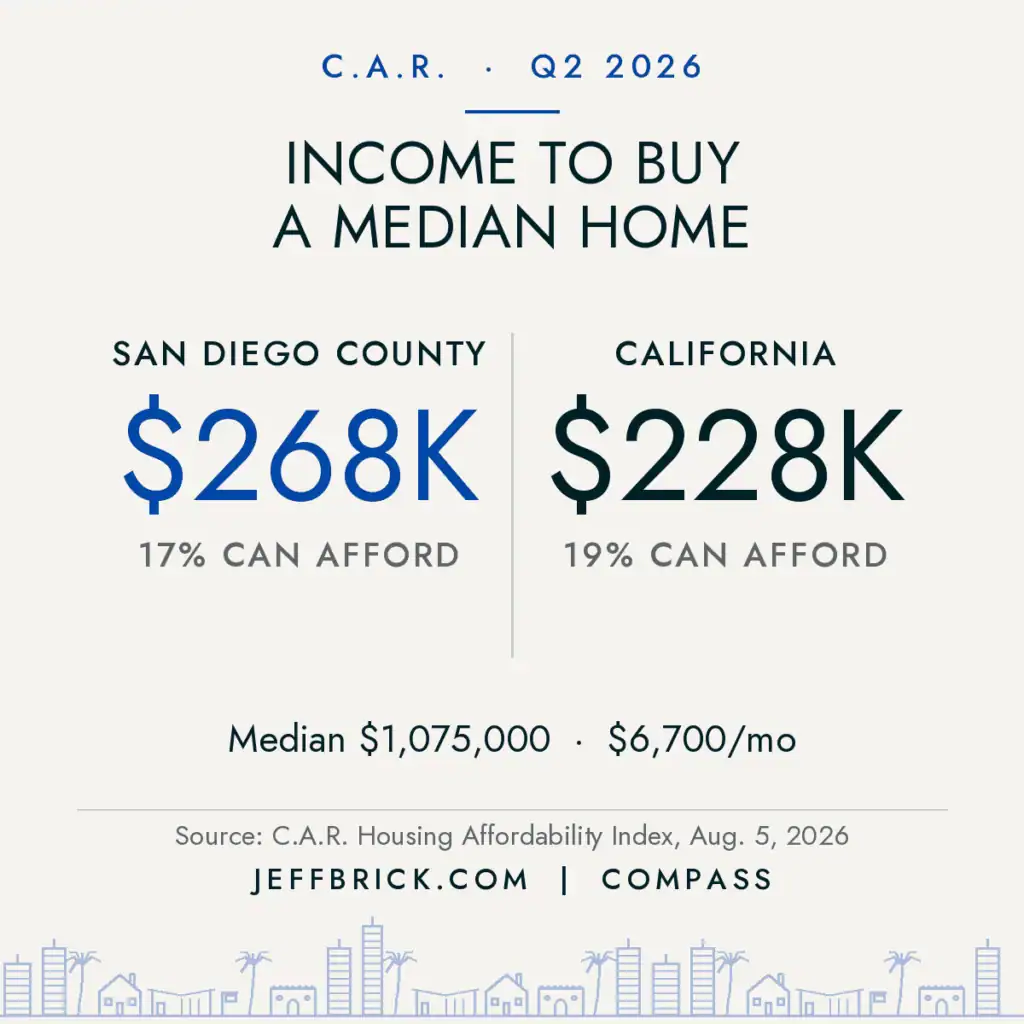
The California Association of REALTORS® (C.A.R.) tracks this every quarter. For the second quarter of 2026, it found a San Diego County buyer needed a minimum qualifying income of $268,000 to buy the $1,075,000 median-priced home, with a monthly payment of $6,700 including taxes and insurance. Only 17% of county households could afford it, versus 19% statewide, where the qualifying income was $228,400.
Two things to know about that number. First, C.A.R. assumed 20% down and a 6.54% rate. At this week’s 7.32%, the principal and interest on that same loan rises from about $5,458 to about $5,908 a month, by my math. Second, C.A.R.’s figures work out to housing costs of about 30% of gross income. Lenders often allow more than that, but 30% is a healthy target for a first home.
Down payment: less than you think, more than you’d like
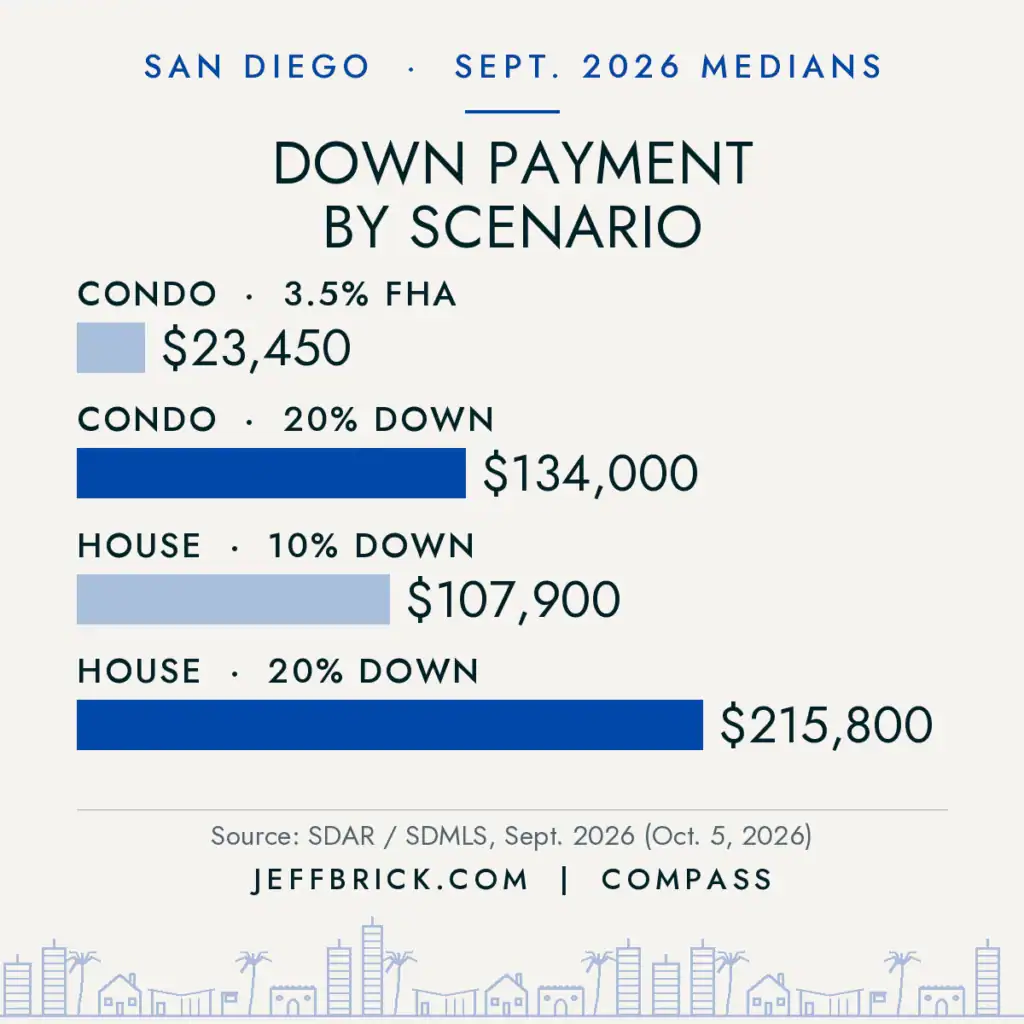
The myth I hear most is “I need 20% down.” You don’t. Fannie Mae’s HomeReady program allows as little as 3% down for eligible buyers, and FHA loans start at 3.5%. The trade-off is mortgage insurance and a bigger loan. Here is what the medians look like:
- Condo, 3.5% down (FHA): $23,450
- Condo, 20% down: $134,000
- House, 10% down: $107,900
- House, 20% down: $215,800
Loan size matters too. In 2026 the conforming loan limit for a one-unit home in San Diego County is $1,104,000 (the national baseline is $832,750, per FHFA), and the county’s FHA limit is also $1,104,000. A median house with 10% or 20% down stays under that line; go much above about $1.2 million with 10% down and you are in jumbo territory, which usually means stricter rules.
Closing costs and cash to close
Budget for closing costs on top of the down payment. Chase and Bankrate both put typical buyer closing costs at 2% to 5% of the loan amount (Bankrate), covering lender fees, escrow, title insurance, prepaid interest and the first months of taxes and insurance. Using that range:
- Median condo, 3.5% down: about $12,900 to $32,300 in closing costs, or roughly $36,000 to $56,000 total cash to close.
- Median house, 20% down: about $17,300 to $43,200 in closing costs, or roughly $233,000 to $259,000 total.
Then keep reserves. I like to see buyers hold a few months of payments in savings after closing, because the water heater never asks for permission.
The monthly payment, line by line
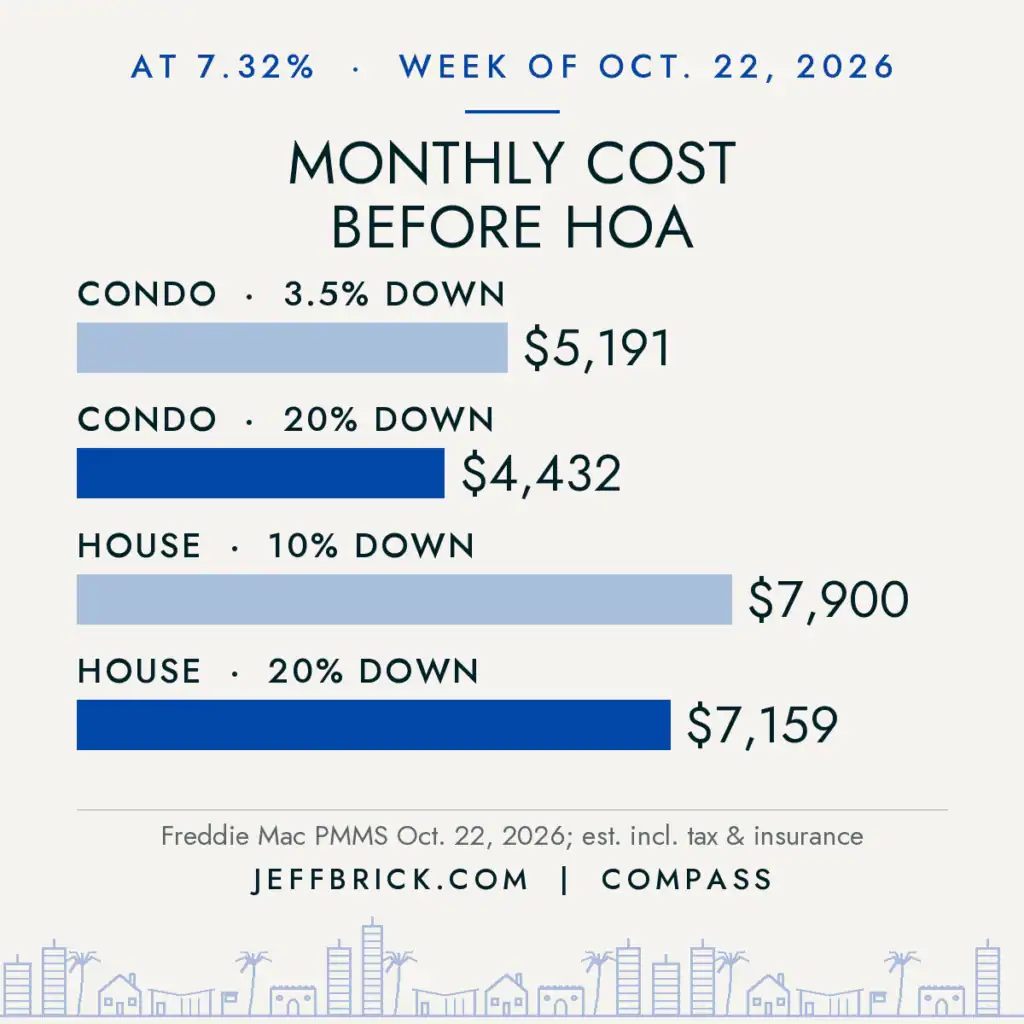
Here are my estimates at 7.32% on a 30-year fixed, including principal, interest, property tax and homeowners insurance. For property tax I used 1.2% of the price as a planning estimate: California’s base levy is 1% of assessed value, and local bonds and assessments add to it depending on the address. These numbers do not include HOA dues or mortgage insurance.
- Condo, 3.5% down: about $5,191 a month, which suggests an income near $208,000 at 30%.
- Condo, 20% down: about $4,432 a month, or an income near $177,000.
- House, 10% down: about $7,900 a month, or an income near $316,000.
- House, 20% down: about $7,159 a month, or an income near $286,000.
Ways first-time buyers close the gap
Start with a condo or townhome
With condo prices flat and a 4.0-month supply, this is the part of the market where first-time buyers have leverage. Ask about HOA dues, reserves and any special assessments before you fall in love. My fall 2026 first-time buyer neighborhood guide shows where your budget goes furthest.
Look at down payment help
CalHFA runs state programs, including the California Dream For All shared appreciation loan, which opens in funding rounds. Program rules change, so check CalHFA directly and ask a CalHFA-approved lender. I’ll go deeper on San Diego County programs next week.
Ask the seller for help
Where homes are sitting longer, seller credits toward closing costs or a rate buydown can be worth more than a small price cut. Your lender can show the payment both ways.
If you rent today
Line up your lease end date with your buying timeline so you are not paying rent and a mortgage at once. If you are still weighing it, my rent-or-buy breakdown runs the numbers side by side.
Jeff’s take
I’ve helped buyers in San Diego since 1999, and the people who win their first home are rarely the ones with the biggest income. They’re the ones who know their number before they tour. As the 2026 President of the San Diego Multiple Listing Service, a Board Director of the San Diego Association of REALTORS® and the largest luxury apartment home leasing broker in Southern California, I see both sides every day: renters stretching for rent and buyers wondering if they can ever get in. My advice is simple. Get fully pre-approved, know your cash-to-close range, and target the condo and townhome market where you have room to negotiate. Million Dollar Service at All Price Points means a $670,000 condo gets the same strategy as a $3 million estate.
Let’s find your number
Want a personal “how much do I need” plan, with a lender I trust running your real numbers? Call or text me at 858-324-4448 or reach out at jeffbrick.com. Every buyer, every family and every budget is welcome. For more first-time buyer basics, start with my top 5 tips for first-time homebuyers.
FAQ
How much do you need to buy a house in San Diego?
For the September 2026 median detached house of $1,079,000, plan on about $233,000 to $259,000 in cash with 20% down, and an income near $290,000. A median condo at $670,000 can take about $36,000 to $56,000 in cash with an FHA loan.
What income do you need to buy a home in San Diego County?
C.A.R. put the minimum qualifying income at $268,000 for the Q2 2026 median-priced home of $1,075,000, assuming 20% down and a 6.54% rate. At today’s higher rates, the figure is higher.
Can I buy in San Diego with less than 20% down?
Yes. Fannie Mae’s HomeReady allows as little as 3% down for eligible buyers, and FHA loans start at 3.5%. Expect mortgage insurance with lower down payments.
How much are closing costs in San Diego?
Buyer closing costs typically run 2% to 5% of the loan amount, which is roughly $12,900 to $32,300 on an FHA loan for a median condo.
What is the 2026 conforming loan limit in San Diego County?
$1,104,000 for a one-unit home, and the FHA limit is also $1,104,000. Loans above that are jumbo loans.
Jeff Brick, REALTOR® at Compass, DRE# 02156850. 2026 President, San Diego Multiple Listing Service; Board of Directors, San Diego Association of REALTORS® (2024–2026); the largest luxury apartment home leasing broker in Southern California.