Published · By Jeff Brick, 2026 SDMLS President
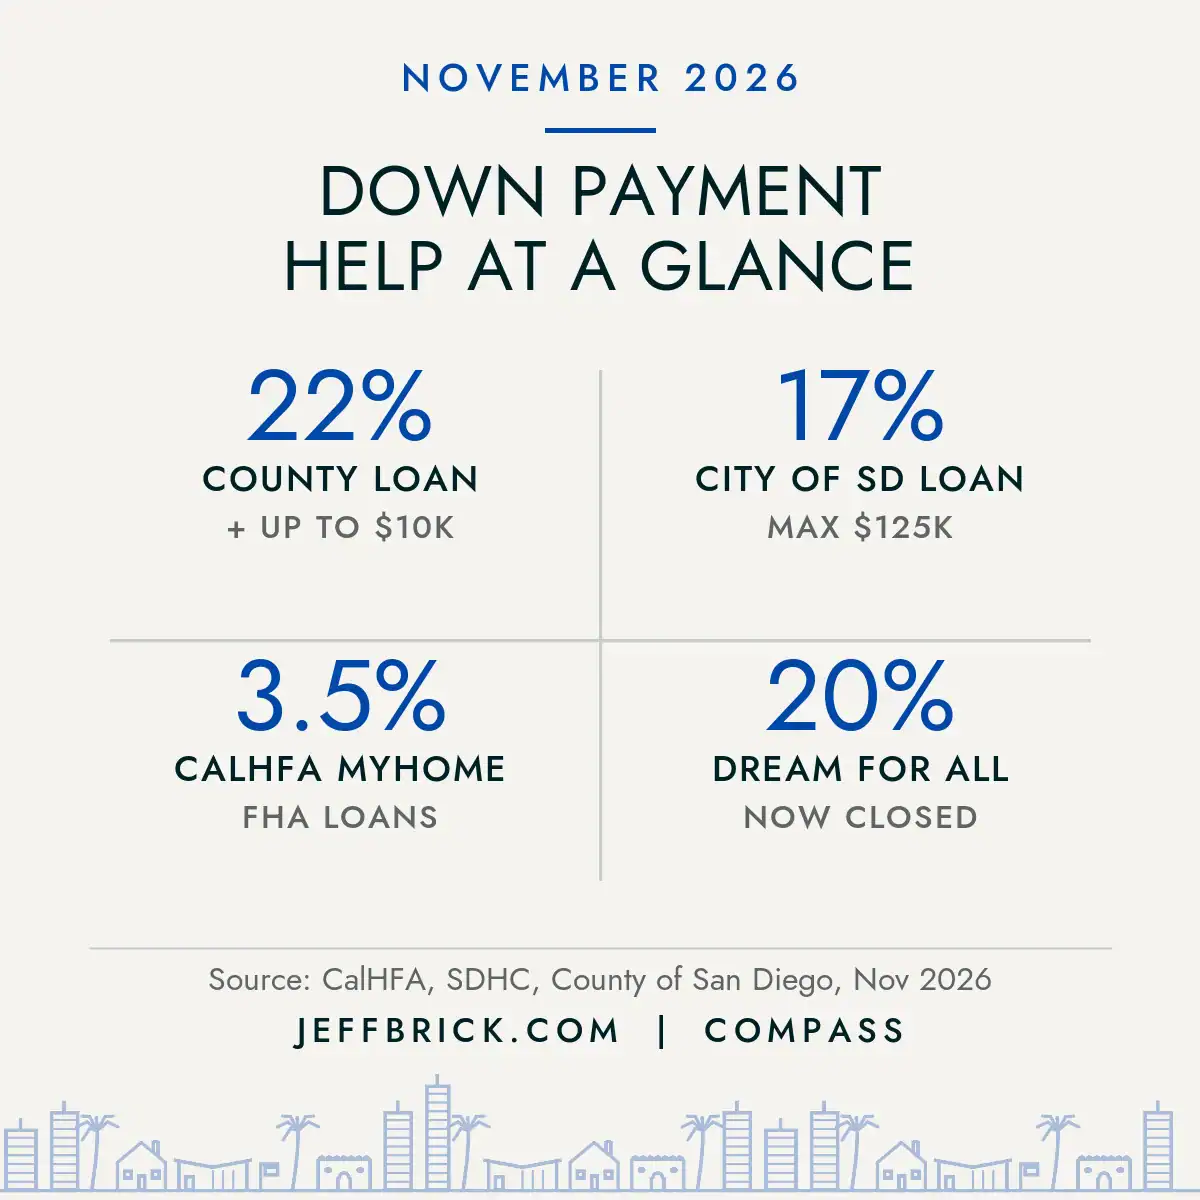
Quick answer: Down payment assistance in San Diego County comes from three main places: the state (CalHFA), the San Diego Housing Commission for homes inside the City of San Diego, and the County of San Diego for unincorporated areas and partner cities. Right now the biggest local help is a deferred loan of up to 17% of the price (max $125,000) inside the city and up to 22% in County program areas, each with up to $10,000 toward closing costs, for households at or under 80% of area median income. CalHFA’s MyHome loan adds up to 3.5% statewide. The popular Dream For All program is closed to new applications for now.
This is general information, not legal, tax or financial advice. Program rules and funding change often, so confirm current terms with a CalHFA- or SDHC-approved lender before you write an offer.
Why down payment help matters in San Diego right now
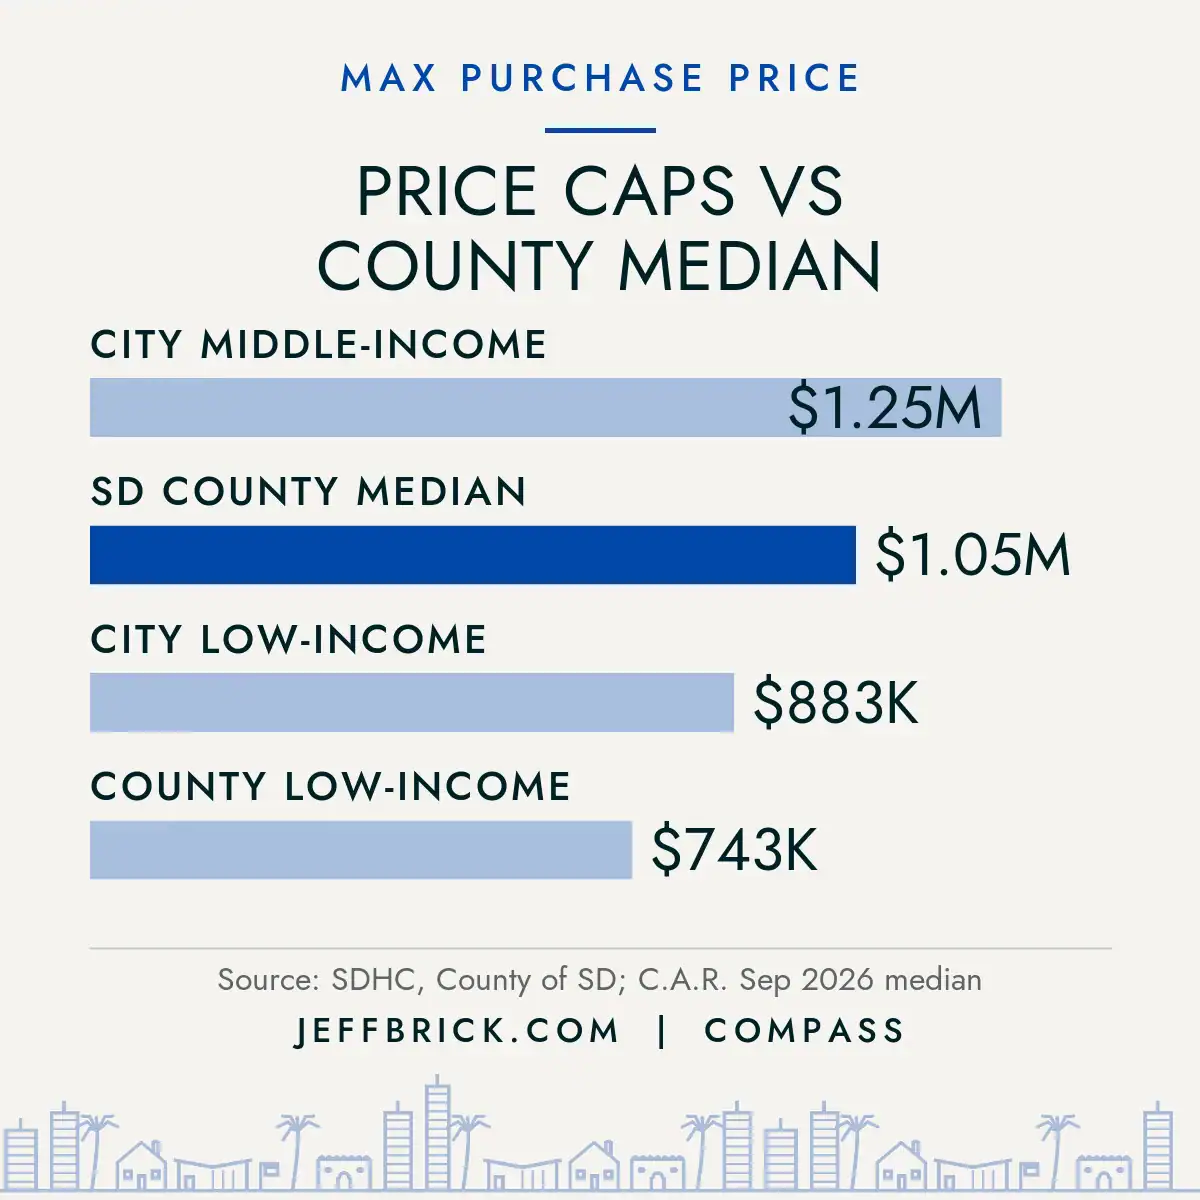
The math is the whole story. The median existing single-family home in San Diego County sold for $1,050,000 in September 2026, up 6.1% from a year earlier, according to the California Association of REALTORS®. At the same time, Freddie Mac’s survey put the average 30-year fixed rate at 7.24% on Oct. 29, 2026, down from 7.32% the week before but well above the 6.17% of a year ago.
For most first-time buyers, the barrier isn’t the monthly payment alone. It’s the cash: down payment, closing costs and reserves, all while paying San Diego rent. That’s exactly the gap these programs were built to close. If you haven’t yet worked out your own cash-to-close range, start with my guide on how much you need to buy a home in San Diego, then come back here.
State programs: CalHFA
MyHome Assistance Program
CalHFA’s MyHome is a deferred-payment junior loan you pair with a CalHFA first mortgage. It covers up to 3.5% of the price on an FHA loan, or up to 3% on a conventional loan, and you make no payments on it until you sell, refinance or pay off the first loan. You must be a first-time buyer, live in the home, meet CalHFA’s county income limits and complete homebuyer education (CalHFA lists an eight-hour online eHome course for $100, or a HUD-approved counselor). Non-occupant co-borrowers aren’t allowed.
California Dream For All
Dream For All is the shared-appreciation loan everyone asks about: up to 20% of the price, not to exceed $150,000. Instead of interest, you repay the original amount plus a share of your home’s appreciation when you sell, transfer or pay it off (CalHFA’s examples show 20% of appreciation, reduced to 15% for borrowers at or below 80% of area median income). At least one borrower must be a first-generation homebuyer. The catch for today: CalHFA says the voucher application period is “now CLOSED,” after the most recent portal closed March 16, 2026, and vouchers are awarded by random drawing. Watch for the next round, and get pre-approved with a CalHFA lender now so you’re ready.
CalHFA also lists its CalPLUS first mortgages, which can be paired with its Zero Interest Program (ZIP) for closing costs, on its homebuyer programs page. Ask your lender which combination fits your file.
Local programs: City and County of San Diego
Both local programs are run through the San Diego Housing Commission (SDHC), which listed funds as available for each program on its first-time homebuyer page when I checked this week. The key question is where the home is.
City of San Diego (ZIP codes starting with 921)
The low-income program (household income at or under 80% of area median) offers a deferred loan of up to 17% of the price, not to exceed $125,000, at 3% simple interest with no payments for 30 years unless you sell or move out. It adds a forgiven closing-cost grant of 4% of the price, up to $10,000. The maximum purchase price is $883,025 for attached or detached homes, and you bring at least 3% of your own. That covers city neighborhoods like North Park, Clairemont and Mira Mesa, where condos and townhomes can land under that cap.
For middle-income buyers (80% to 150% of area median), SDHC offers a $40,000 deferred loan at 4% simple interest plus a $10,000 closing-cost grant, with a $1,250,000 maximum price. No payments are due in years one through five; after that the balance becomes a 10-year amortized loan.
County of San Diego (unincorporated areas and partner cities)
The County’s Down Payment and Closing Cost Assistance program offers a deferred loan of up to 22% of the price, plus 4% up to $10,000 for closing costs, for households at or under 80% of area median income. The price cap is $743,000. Eligible areas include unincorporated San Diego County plus Coronado, Del Mar, Imperial Beach, Lemon Grove, Poway and Solana Beach, along with HOME Consortium cities Carlsbad, Encinitas, La Mesa, San Marcos, Santee and Vista. You can’t have owned a home in the past three years.
There’s also a newer County moderate-income option for households earning 80% to 120% of area median. Its June 2026 guidelines allow up to 17% of the price at 3% simple interest, deferred 30 years, in the unincorporated area and six cities. For a family of four, that band runs from $139,900 to $157,100 in income. It requires a 640 minimum credit score, caps total debt-to-income at 45%, and funds are “first-come, first-served.” Chula Vista runs its own program through SDHC as well.
What the help looks like on a real purchase
Here’s a simple example using the City low-income program on a $600,000 condo. The 17% loan is $102,000. The closing-cost grant is 4%, capped at $10,000. You bring the 3% minimum, $18,000. That leaves a first mortgage of about $480,000 instead of $582,000 with 3% down alone. At the 7.24% average rate, principal and interest drop from about $3,966 to $3,271 a month, roughly $695 less, before taxes, insurance and HOA dues. Remember that the 3% interest on the deferred loan still adds up (about $3,060 a year on $102,000) and is repaid when you sell or refinance. Your lender’s actual rate and fees will differ.
How to apply, step by step
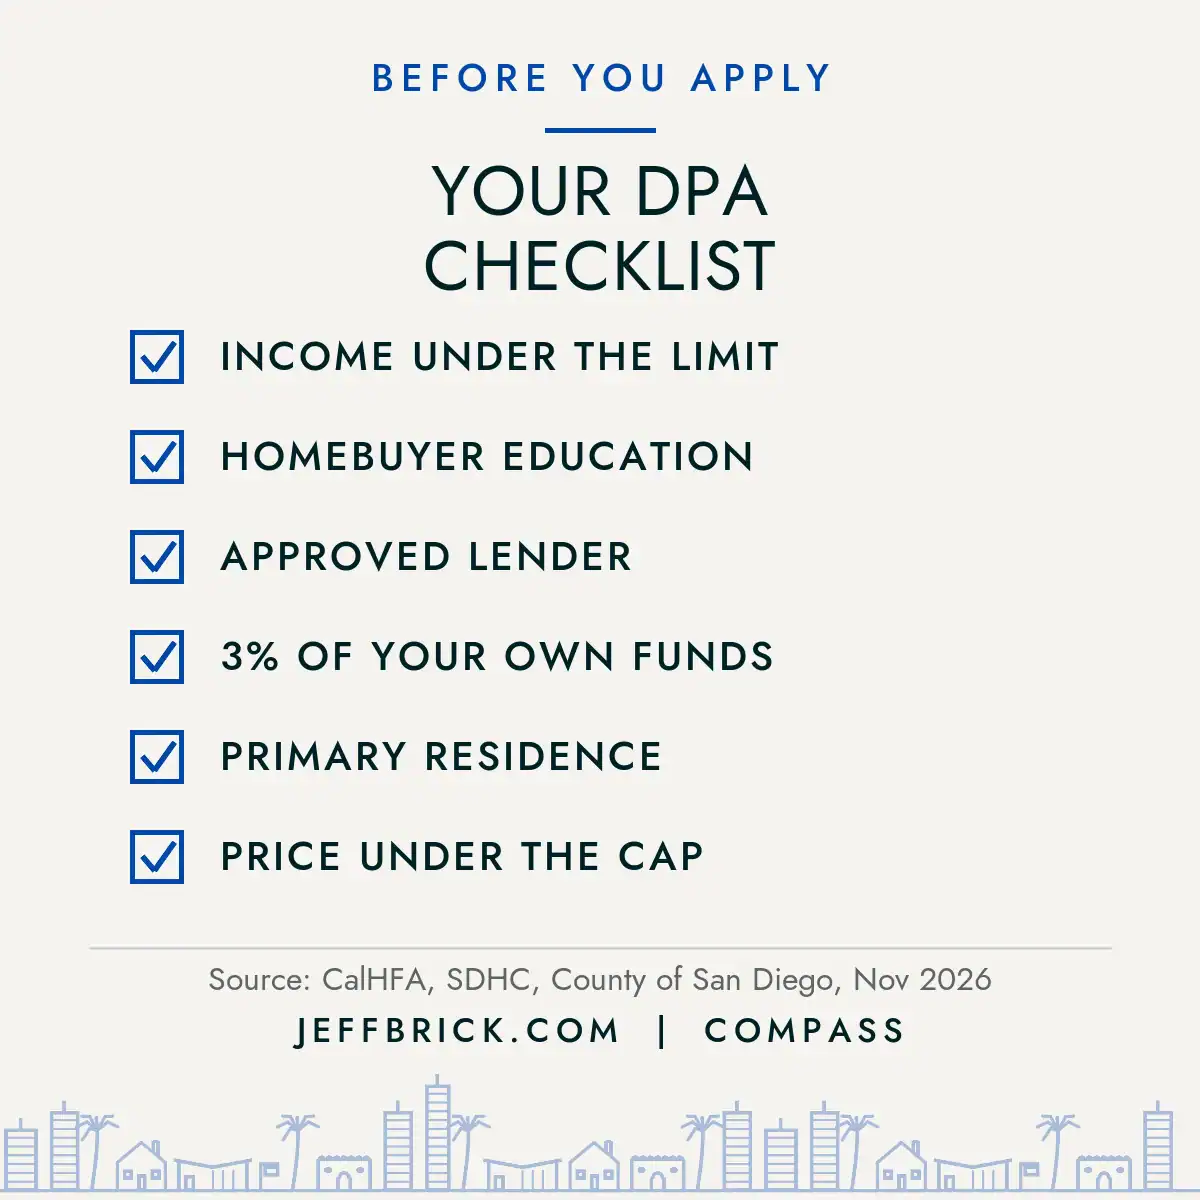
- Check your household income against the 2026 limits (SDHC posts its AMI table; CalHFA posts county limits by program).
- Take an approved homebuyer education course. Most programs require one.
- Choose a lender on the CalHFA or SDHC participating list. The lender submits the assistance application, not you.
- Get fully pre-approved with the assistance built in, so your offer shows the right numbers.
- Shop within the price cap and the right area, then confirm the property type qualifies before you write an offer.
A note for renters
If you’re renting today and your lease ends in spring, now is the time to finish homebuyer education and get pre-approved. None of these programs require you to break a lease to apply, and having your paperwork ready means you can move when the right condo shows up instead of scrambling.
Jeff’s take
I’ve been helping San Diego buyers since 1999, and down payment assistance is the most underused tool I see. Buyers assume they earn too much, or that the money’s gone, and never ask. As the 2026 President of the San Diego Multiple Listing Service, a Board Director of the San Diego Association of REALTORS® and the largest luxury apartment home leasing broker in Southern California, I talk with renters every week who are closer to owning than they think. My advice: pick the program by where you want to live, line up an approved lender early, and write offers that sellers trust. Assistance-backed offers can win when they’re clean and well prepared. That’s Million Dollar Service at All Price Points.
Let’s map your down payment plan
Want to know which program fits your income and your neighborhood shortlist? Call or text me at 858-324-4448 or reach out at jeffbrick.com. Every buyer and every family is welcome home. Browse all of my San Diego neighborhood guides, and see my fall 2026 first-time buyer neighborhood guide for where these price caps go furthest.
FAQ
Is there down payment assistance in San Diego in 2026?
Yes. The City of San Diego offers up to 17% of the price (max $125,000) and the County offers up to 22% for households at or under 80% of area median income, each with up to $10,000 for closing costs. CalHFA’s MyHome adds up to 3.5% statewide.
Is CalHFA Dream For All open right now?
No. CalHFA says the Dream For All voucher application period is closed; the most recent portal closed March 16, 2026. Watch CalHFA’s site for the next round.
What is the income limit for San Diego down payment assistance?
The main City and County programs cap income at 80% of San Diego area median income, which is $139,900 for a family of four under the June 2026 limits. The City middle-income program goes up to 150% and the County moderate-income program up to 120%.
Do I have to pay down payment assistance back?
Usually, yes, but later. Most are deferred loans repaid when you sell, refinance or move out. The City’s closing-cost grant of up to $10,000 is forgiven.
Can I use these programs for a condo?
Yes. Single-family homes, townhomes and condos generally qualify, as long as the price is under the program cap and you live there as your primary residence.
Jeff Brick, REALTOR® at Compass, DRE# 02156850. 2026 President, San Diego Multiple Listing Service; Board of Directors, San Diego Association of REALTORS® (2024–2026); the largest luxury apartment home leasing broker in Southern California.