Published · By Jeff Brick, 2026 SDMLS President
Quick answer: How much house can I afford San Diego is really a monthly-payment question, and at today’s 7.11% average 30-year rate a $4,500 principal-and-interest budget supports about $668,900 of loan, roughly $62,700 less than the same budget supported at last year’s 6.24%. Rates move your buying power faster than most prices move your costs, so run the payment before you fall in love with a listing.
I’m Jeff Brick, a San Diego REALTOR® with Compass and the 2026 President of the San Diego Multiple Listing Service. Every week a buyer asks me some version of “what can I afford?”, and the honest answer starts with the rate, not the price. Here is how I walk buyers through it. This is general information, not legal, tax or financial advice, so confirm your numbers with a licensed lender.
Where rates stand this week
Freddie Mac’s weekly survey put the 30-year fixed rate at 7.11% as of November 12, 2026, down from 7.18% a week earlier and up from 6.24% a year ago, according to Freddie Mac’s November 12 release. The 15-year fixed averaged 6.45% in the same survey. Rates have now dropped four weeks in a row, which helps, but they are still nearly a full point above where they stood a year ago.
How rates change the monthly payment
Take an $800,000 loan, which is what a buyer needs on a $1,000,000 home with 20% down. Using the standard 30-year payment formula and the Freddie Mac averages above, the principal-and-interest payment works out like this:
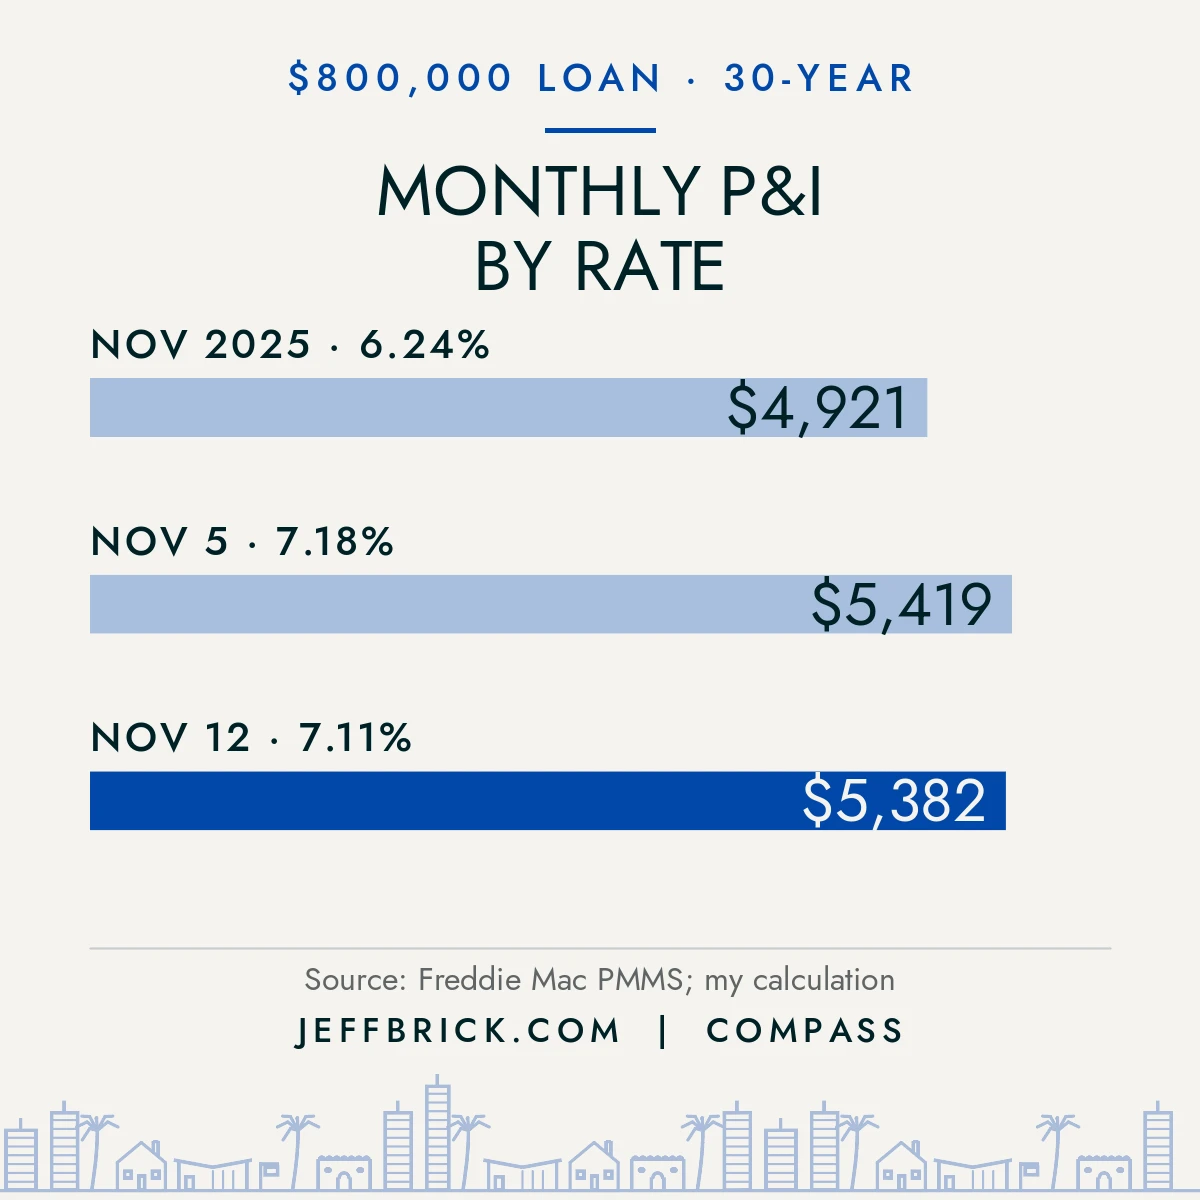
That is about $461 more every month, or roughly $5,500 more per year, than the same loan cost at last year’s rate. The house did not change. The payment did. Those figures are my own calculations from the Freddie Mac rates and exclude property tax, insurance and any HOA dues, which all add to your real monthly cost.
How much house can I afford San Diego buyers can plan for on a fixed budget
Flip the question around. If your comfortable principal-and-interest budget is $4,500 a month, here is the loan it supports:
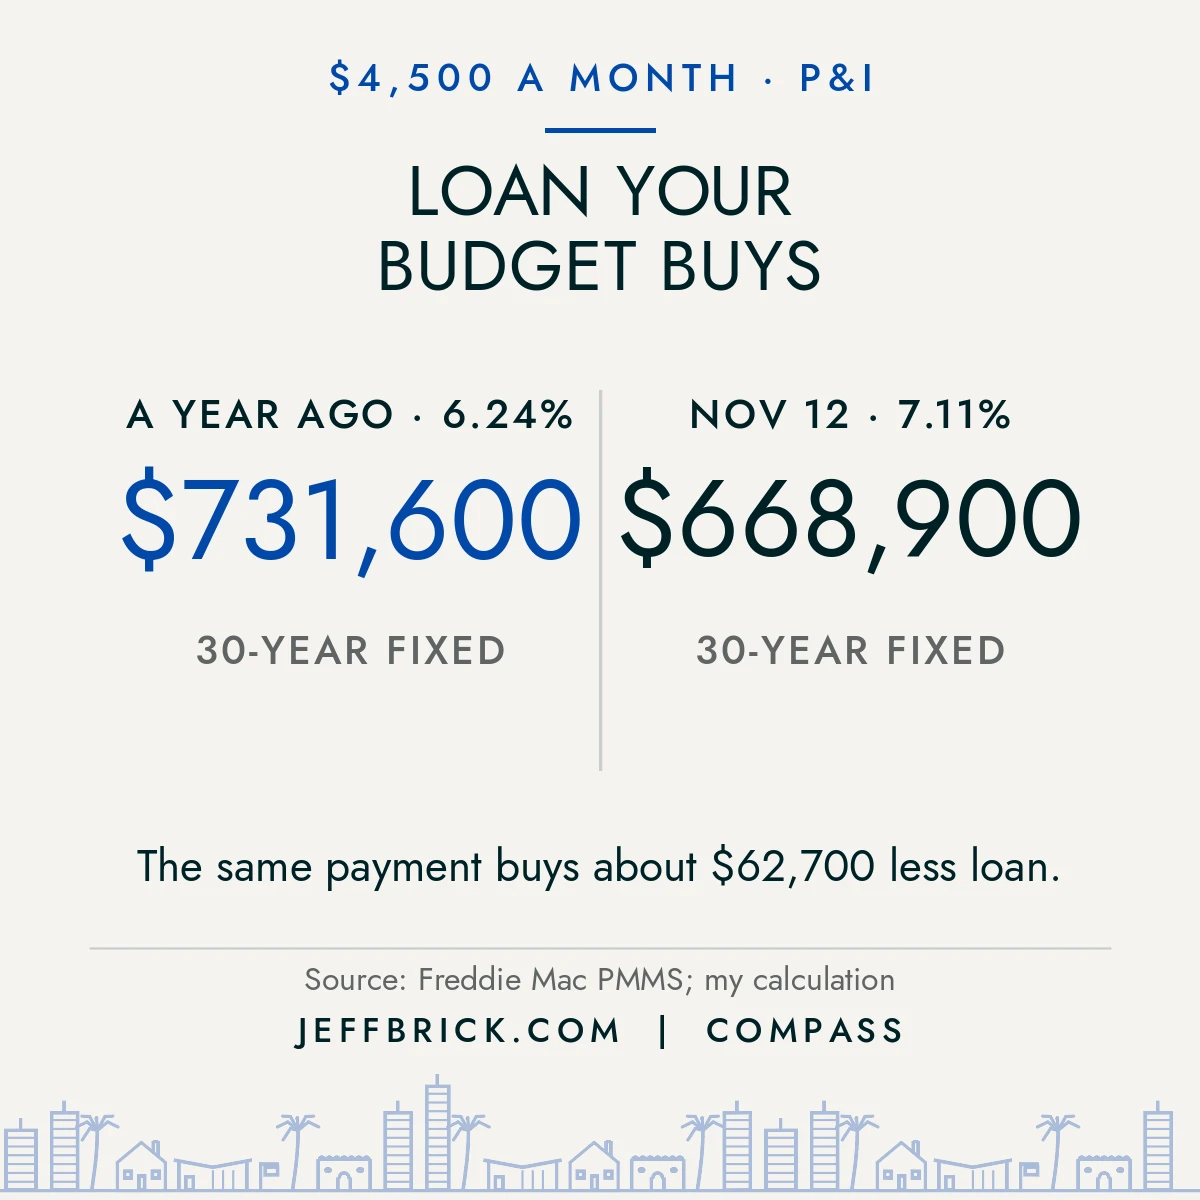
With a 20% down payment, that gap is about $78,000 of purchase price on the same monthly budget (my calculation). It is the clearest way I know to explain why a rate drop can feel like a price cut. Every quarter point matters, so ask your lender to show you the payment at today’s rate and at a rate a half point lower.
What lenders let you borrow: the debt-to-income ratio
Your rate sets the payment, but your debt-to-income ratio (DTI) sets the ceiling. Under Fannie Mae’s Selling Guide, the maximum total DTI is 36% for manually underwritten loans, which can stretch to 45% with strong credit and reserves, and 50% for loans run through its automated underwriting system. Total DTI counts your new housing payment plus car loans, student loans and card minimums, measured against your gross monthly income.
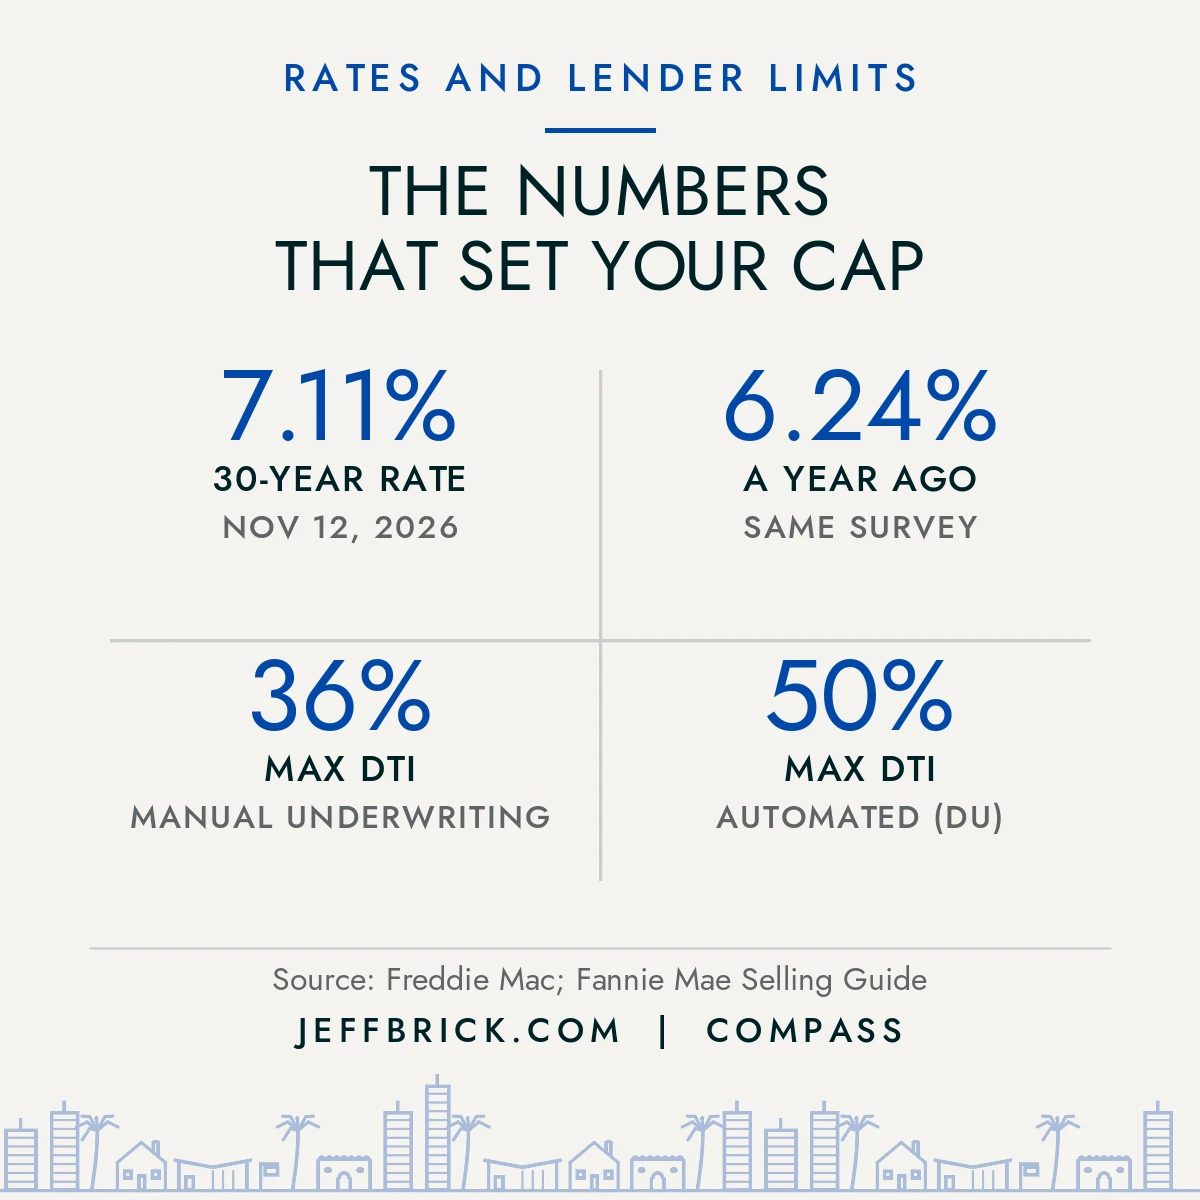
As an example, a household earning $15,000 a month before tax could see a ceiling of about $5,400 in total monthly debt at 36%, or $7,500 at 50%. Being approved for the maximum is not the same as being comfortable. I coach buyers to set a payment they can live with, including travel, dinners out and an emergency fund, then work backward.
Loan size matters too. The 2026 conforming loan ceiling for one-unit homes in high-cost areas is $1,249,125, according to the FHFA. Loans above your county’s limit are jumbo loans with their own pricing and rules, so ask your lender which side of that line your loan falls on.
What a $1 million budget looks like in San Diego
In my October 2026 neighborhood price report, several areas sat near the $1 million mark for a single-family home. All figures are San Diego MLS, October 2026, medians for houses: Mira Mesa at $1,030,000, Otay Ranch at $1,029,500, Allied Gardens and Del Cerro at $992,500, Mount Helix at $990,000 and Escondido at $985,000. Some of those areas had fewer than 10 sales that month, so treat them as a snapshot, not a trend. You can browse every area on my neighborhood guides hub.
Remember the extras that sit on top of principal and interest: property tax, homeowners insurance (which can be pricier in wildfire zones) and HOA dues for condos and many newer communities. If you need inspections, a lender or repair estimates before you write an offer, my Approved Vendors list is a good place to start. If you are early in the process, my guide to choosing an agent as a first-time buyer covers the questions to ask.
Five ways to stretch your buying power
First, compare lenders on the same day, because rate quotes vary and a small difference compounds over 30 years. Second, ask what a point of upfront cost buys in rate and how long it takes to break even. Third, look at the areas near your price instead of fixating on one neighborhood. Fourth, ask about seller credits, which can fund closing costs or a temporary rate buydown. Fifth, keep your credit steady, since new debt before closing can change your DTI and your approval.
Jeff’s take
I would rather you buy a home you can enjoy than the largest one a lender will approve. Rates will keep moving, and you can often refinance later if they fall, but you cannot refinance a payment that is stressing your life today. Love is love and math is math, and every family deserves a plan that works on both counts. As a San Diego REALTOR® with Compass, 2026 President of the San Diego Multiple Listing Service and a Southern California luxury apartment home leasing broker, I help buyers and renters at every price point, and I am happy to run your numbers with you. Million Dollar Service at All Price Points is not just a motto for me.
Ready to find your number?
Call or text me at 858-324-4448 and I will walk through your budget, connect you with lenders and show you which San Diego neighborhoods fit. Everyone is welcome home here.
FAQ: rates and buying power in San Diego
How much does a 1% rate change affect my payment?
On an $800,000 30-year loan, the gap between 6.24% and 7.11% is about $461 a month in principal and interest, based on my calculation from the Freddie Mac averages. A full point is a bigger swing than most buyers expect.
What debt-to-income ratio do I need to qualify?
Fannie Mae’s guide lists a 36% maximum for manually underwritten loans (up to 45% with strong credit and reserves) and 50% for automated underwriting. Your lender’s own limits can be stricter, so ask before you shop.
Should I wait for rates to drop before buying?
Nobody can time rates reliably. If you find a home that fits your budget at today’s rate, you can ask about refinancing if rates fall later, though a refinance is never guaranteed. Waiting also carries the risk that prices rise.
Is the conforming loan limit the same everywhere?
No. The FHFA sets a national baseline of $832,750 for 2026 and a high-cost ceiling of $1,249,125 for one-unit homes, with limits varying by county. Ask your lender which limit applies to your county.
What costs besides the mortgage should I budget for?
Plan for property tax, homeowners insurance, HOA dues if they apply, maintenance and closing costs. Your lender’s loan estimate shows an itemized monthly figure, which is the number to compare to your budget.