Published · By Jeff Brick, 2026 SDMLS President
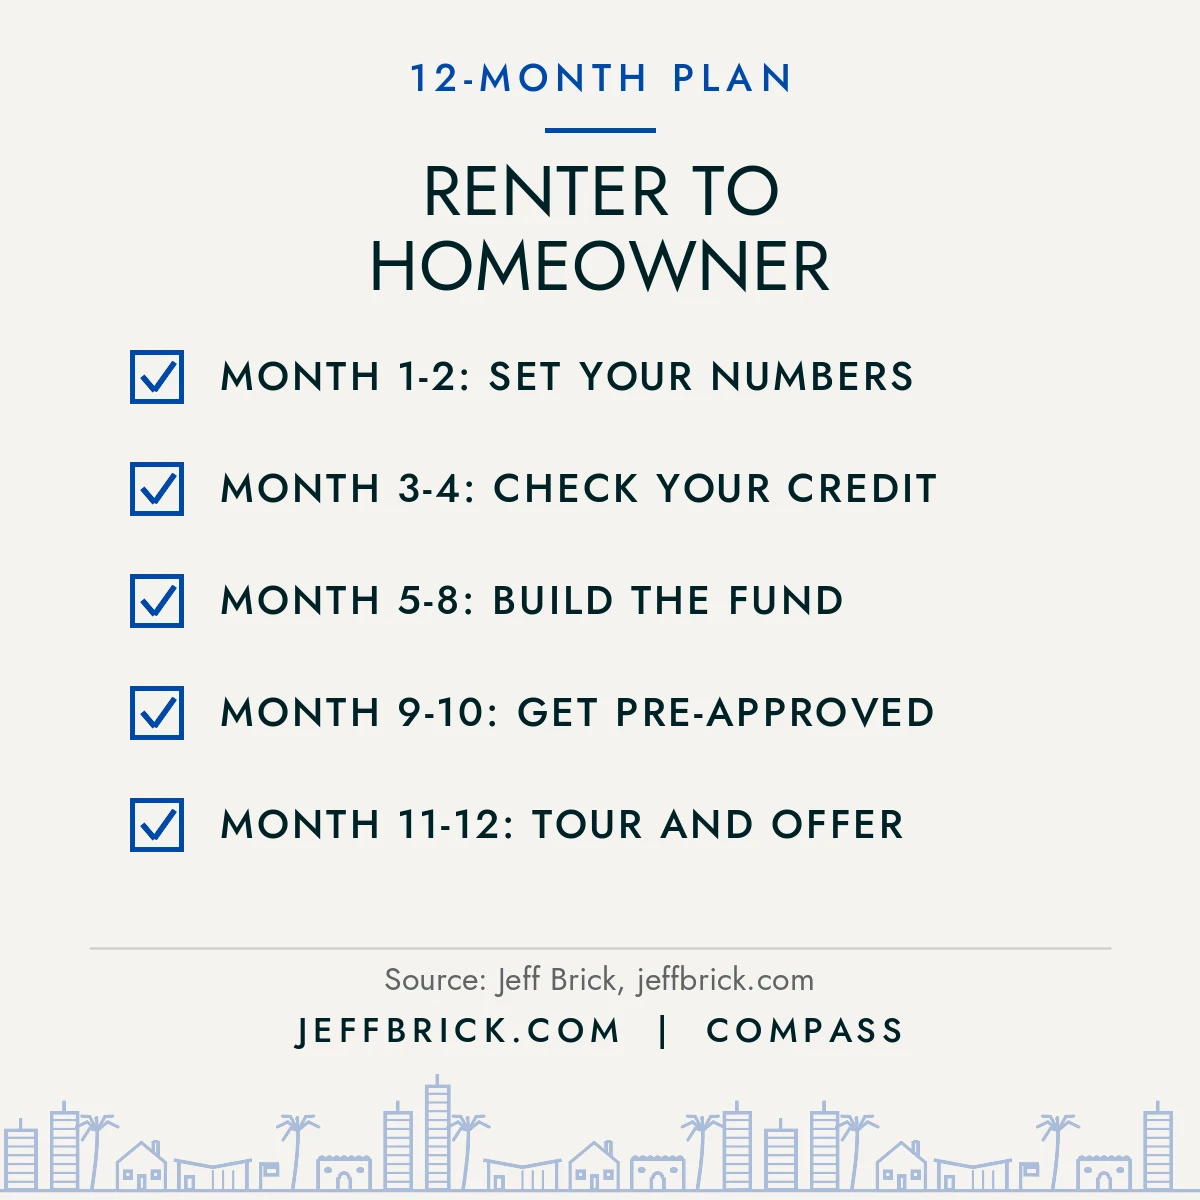
Quick answer: The path from renter to homeowner in San Diego works best as a 12-month plan with five phases: set your numbers, check your credit, build your down payment and cash reserves, get pre-approved, then tour and make offers. Most renters I meet are closer than they think, because the biggest gap is usually a plan, not a paycheck.
I have helped renters become owners since 1999, and the renter to homeowner journey always starts the same way: with one honest look at the numbers. This guide walks through the year month by month. It is general information, not legal, tax or financial advice, so confirm your details with a licensed lender and your tax professional.
Why a 12-Month Renter to Homeowner Plan Works
A year gives you enough time to raise a credit score, save a meaningful down payment and learn the market without rushing. It is also short enough to stay motivated. If you are still deciding whether buying beats renting, start with my rent vs. buy calculator for San Diego, then come back here to build the plan.
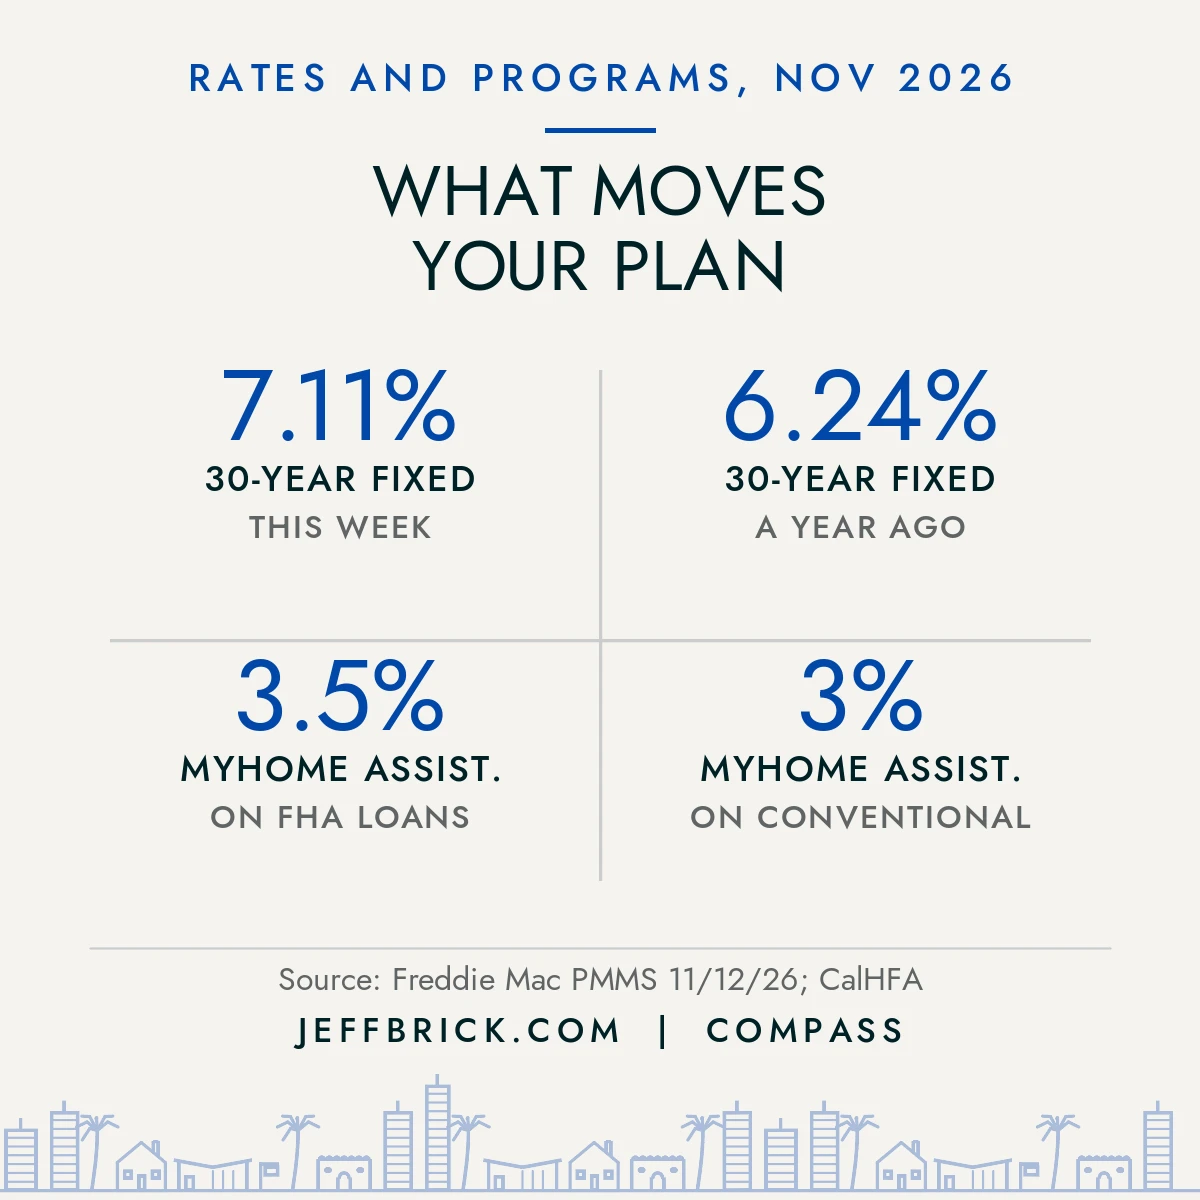
Rates matter to every renter to homeowner decision, so let me be direct about today’s picture. Freddie Mac reported the 30-year fixed-rate mortgage averaged 7.11% in its survey dated November 12, 2026, down for the fourth straight week but above the 6.24% average a year earlier. As a rough guide from my own math, every $100,000 borrowed costs about $673 a month in principal and interest at 7.11%, compared with about $615 at last year’s rate. That is why your budget, not the headline rate, should drive the plan.
Months 1 and 2: Set Your Numbers
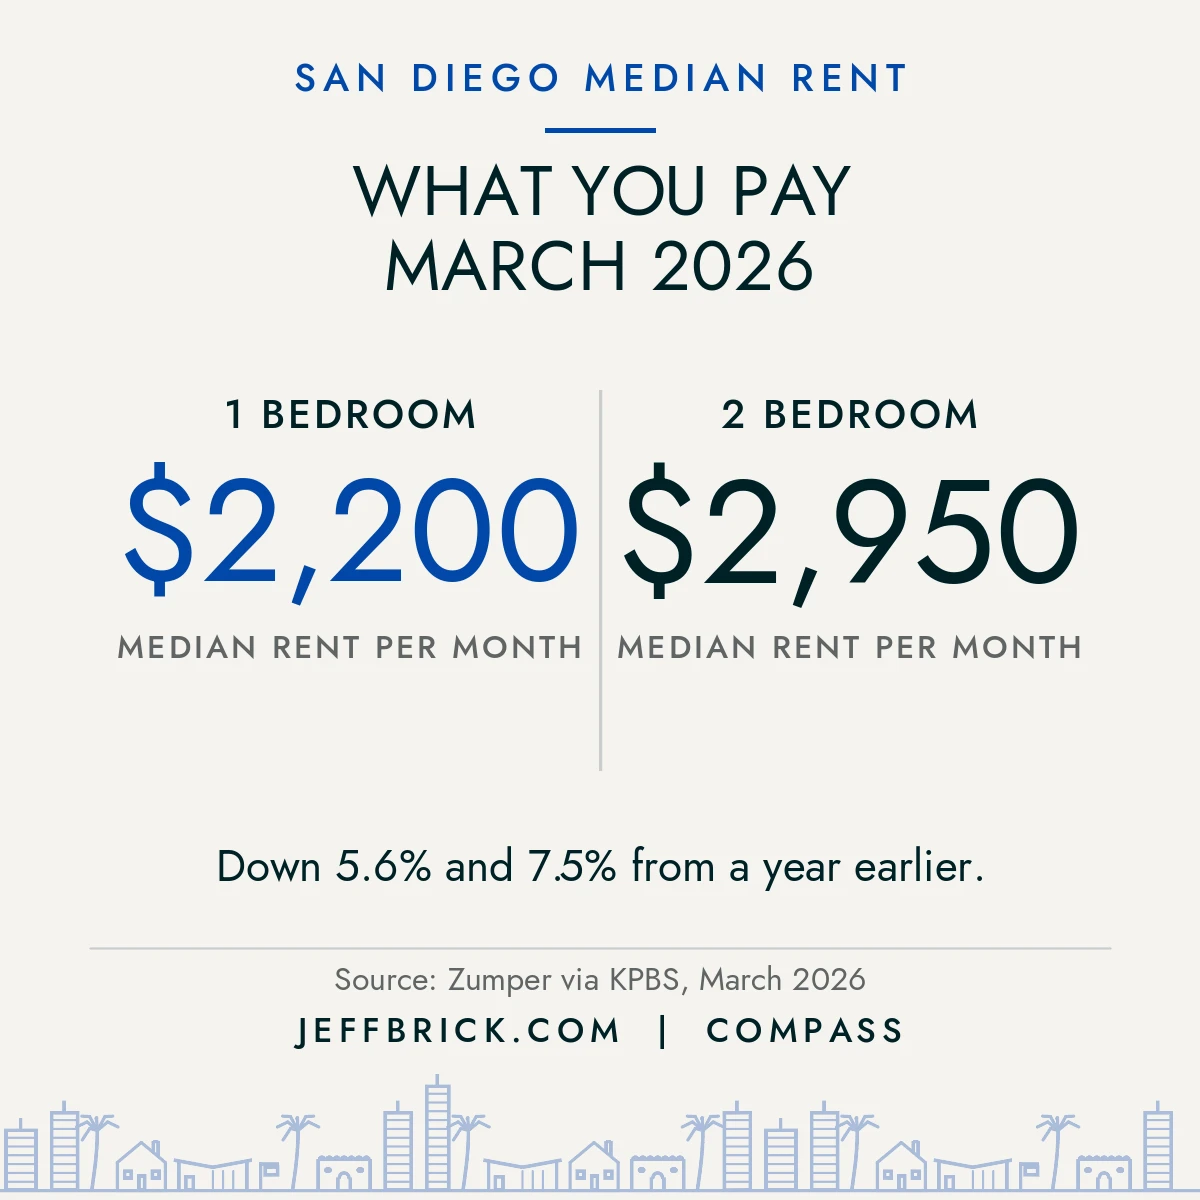
Start with what you pay now. Zumper’s March 2026 report put the median San Diego rent at $2,200 for a one-bedroom and $2,950 for a two-bedroom, down 5.6% and 7.5% from a year earlier, according to KPBS. Northmarq’s Q2 2026 multifamily report showed asking rents at $2,598 a month, essentially flat over the year. Different sources measure rent differently, so use your own lease as the real baseline.
Then build a target monthly payment, not a target price. Add principal, interest, property tax, homeowners insurance and any HOA dues, and compare the total with your rent. My guide on how much house you can afford in San Diego shows how rates change buying power, and how much cash you need to buy a home in San Diego covers the up-front costs.
Months 3 and 4: Check Your Credit and Debts
Credit is the quiet gatekeeper of any renter to homeowner move. Pull your credit reports from all three bureaus at AnnualCreditReport.com and fix any errors early, because disputes take time. Then pay down revolving balances, avoid new credit lines, and keep paying every bill on time. Lenders look at your credit history and your debt-to-income ratio together, so lowering monthly debts can help as much as raising a score.
Do not make big purchases, change jobs without talking to your lender, or move large unexplained sums between accounts while you are in this phase. Plain, well-documented finances make the renter to homeowner process smoother.
Months 5 to 8: Build the Down Payment and Reserves
Open a separate savings account and automate a transfer on payday. Aim to cover the down payment, closing costs and a cash cushion for the first months of ownership, when surprise repairs tend to show up. The down payment help available in San Diego County may stretch your savings further.
One program worth knowing is CalHFA’s MyHome Assistance. Per CalHFA’s program sheet, last revised October 19, 2026, it is a deferred-payment junior loan of up to 3.5% of the sales price or appraised value on FHA loans and 3% on conventional loans, and it must be paired with a CalHFA first mortgage. CalHFA also requires homebuyer education. Income limits and other rules apply, so ask a CalHFA-approved lender whether you qualify.
Months 9 and 10: Get Pre-Approved
Pre-approval turns your plan into a real budget and tells sellers you are serious. Talk to at least two or three lenders, compare the loan estimates side by side, and ask about assistance programs. If you need a lender or other home professionals, my Approved Vendors list is a good place to start.
This is also the right moment to choose an agent. I wrote a plain-English guide on how to choose a real estate agent as a first-time buyer in San Diego with the questions to ask before you sign anything.
Months 11 and 12: Tour, Offer and Close
Now the fun part. Tour homes that fit your target payment, and explore several areas through my neighborhood guides so you compare lifestyle, commute and price. Once you have an accepted offer, my step-by-step San Diego home-buying timeline explains escrow, contingencies and closing. For current pricing, see my San Diego home prices report for November 2026.
That is the full renter to homeowner timeline. Your calendar will not match mine exactly, and that is fine. If life delays a phase, shift the next one rather than abandoning the plan. Keep your savings automatic, keep your credit clean, and review your numbers every month so surprises stay small. When you reach pre-approval, you will already know your payment, your cash needed and the neighborhoods that fit, which puts you ahead of most first-time buyers.
Jeff’s Take
Since 1999 I have worked in this business. Today I serve as 2026 President of the San Diego Multiple Listing Service, sit on the Board of Directors of the San Diego Association of REALTORS®, and work as a Southern California luxury apartment home leasing broker. I see renters at every income level complete the renter to homeowner move with the right sequence. Love is love and math is math: every household is welcome home, and the plan above works for singles, couples and families alike. Start small, stay consistent, and do not let a headline rate scare you out of planning.
Ready to Start Your Renter to Homeowner Plan?
Book a free home-buying consultation or call me at 858-324-4448. I will help you map your first 12 months, step by step. Million Dollar Service at All Price Points.
Renter to Homeowner FAQ
How long does it take to go from renter to homeowner in San Diego?
Many renters can do it in about 12 months with a clear plan, though savings and credit starting points vary. Some are ready sooner, and some need 18 to 24 months.
How much should I save before buying my first home?
Plan for a down payment, closing costs and a cash cushion. The exact amount depends on the price, loan type and any assistance, so ask a lender for a loan estimate.
Is down payment assistance available for San Diego renters?
Yes, programs exist. CalHFA’s MyHome Assistance offers a deferred-payment junior loan of up to 3.5% on FHA loans and 3% on conventional loans, with income limits and required homebuyer education.
Should I wait for mortgage rates to fall?
Nobody can time rates reliably. Build your plan now so you are ready whenever your numbers work, and ask your lender about refinancing options if rates fall after you buy.
Do I need a real estate agent to buy my first home?
You are not required to use one, but an agent helps you price offers, negotiate and manage deadlines. Ask what the agent does for buyers and how they are paid before you commit.